The St. Augustine Buyer's Guide: Insurance, CDDs, Short-Term Rentals, and What Only a Local Agent Can Tell You
Buying a home in St. Augustine, Florida is not like buying a home in most American cities. The market here carries layers of complexity that go well beyond square footage and school ratings. There are CDD fees that confuse even experienced homeowners. There are insurance realities that bear almost no resemblance to the horror stories circulating on national real estate forums. There are short-term rental rules that change from one block to the next in the historic district. And there is a development pipeline that is actively reshaping entire sections of St. Johns County in ways that a newcomer relying only on listing data has no way to anticipate.
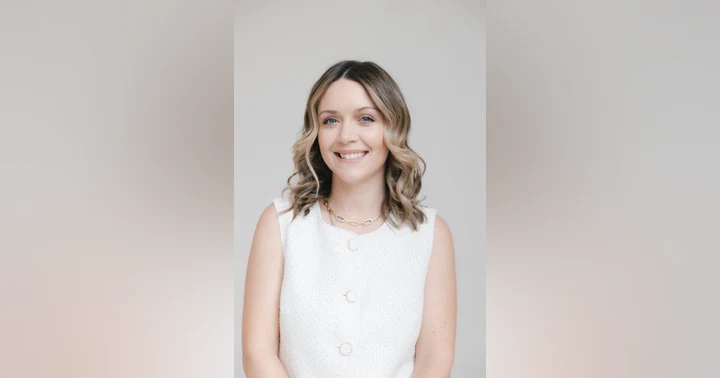
Niki Sparks, the founder of Keller Williams Atlantic Partners St. Augustine and a native of the city whose family has called northeast Florida home since 1565, has spent her real estate career translating these complexities into clear, actionable guidance for buyers. Her approach, built entirely on relationship and referral rather than cold outreach, has made her one of the top-producing agents in the St. Augustine market. In a recent conversation on the Real Estate Excellence Podcast, she offered an unusually candid and detailed look at the issues that trip up buyers most often, and how a truly knowledgeable local agent can help them navigate each one.
The Truth About Florida Insurance in Northeast Florida
Few topics generate more anxiety among buyers considering a move to Florida than homeowners insurance. National headlines about skyrocketing premiums, insurers withdrawing from the state, and the costs of hurricane coverage have created a perception that affordable coverage is impossible to obtain. Niki pushes back on that narrative with historical data and regional specificity.
"I think there's a misconception out there that it's just impossible to get insurance in Florida, and you can't afford it, so you can't afford to come to Florida, and that's just not the case," Niki said. She added a pointed observation about where the real affordability challenge lies: "It's the taxes where you're at that you can't afford."
The geographic distinction matters enormously. Northeast Florida, including St. Augustine and St. Johns County, does not sit in the path of hurricanes the way South Florida does. Niki draws on historical patterns to reassure buyers that the region rarely receives a direct hit, even though flooding can occur in specific low-lying areas. The insurance picture here looks substantially different from what buyers might encounter in Miami or Tampa.
She also corrects a common flood zone misconception. Not all of coastal St. Augustine requires flood insurance. There are properties on Anastasia Island, including some in areas that have never flooded in recorded memory, that fall entirely outside designated flood zones. Understanding exactly where a specific property sits relative to these designations is part of the due diligence Niki conducts on behalf of every buyer.
For older homes, Niki is proactive about addressing the factors that insurance companies scrutinize most closely. Roof age is chief among them. She has arranged for roofing companies to replace a roof at closing, with the cost rolled into the sale price, specifically to ensure a buyer can obtain coverage at a reasonable rate. She also partners with a homeowners insurance specialist who reviews each client's situation individually to find the right policy rather than defaulting to the first available option.
A detail that many agents overlook: when a seller has an existing flood insurance policy, transferring that policy to the buyer can save thousands of dollars compared to obtaining new coverage. Niki treats this as a standard part of her transaction management process, not an afterthought.
"If the buyer can't afford insurance on the home because these updates aren't made, then the buyer can't afford the home. So we make it as attainable as possible."
Understanding CDDs: What the Fee Actually Covers and What Most Buyers Get Wrong
Community Development Districts, commonly called CDDs, are a feature of Florida residential development that consistently surprises buyers relocating from other states. The confusion is understandable. CDDs appear on property tax bills as a separate line item, they are not always clearly disclosed during a home search, and the two-part structure of the fee creates additional layers of misunderstanding.
Niki explains CDDs to her buyers with characteristic directness. The CDD fee covers the cost of the infrastructure and amenities associated with large planned communities: roads, schools, police and fire stations, common areas, pools, trails, and all the other features that make communities like Nocatee, Palencia, and Julington Creek function as self-contained environments.
The fee has two components. The first is a bond, typically structured over 25 or 30 years, that represents the original development financing. The second is an ongoing maintenance fee that remains in place indefinitely. This distinction is where buyers frequently get confused. When a listing notes that the CDD bond has been paid off, some buyers assume there is no longer any CDD obligation. That assumption is incorrect.
"Don't think that just because the bond portion of the CDD is paid off, you're not ever gonna have that again. They can actually renew that bond and it comes back," Niki noted. The maintenance fee, which covers the ongoing operation of community infrastructure and amenities, never goes away entirely.
There is also a practical trade-off worth understanding. Communities with CDD fees typically have lower HOA fees, sometimes as little as 100 to 200 dollars per year. Communities without CDDs often carry HOA fees of 300 to 400 dollars per month because the developer passed the infrastructure costs directly into home prices and ongoing association assessments rather than distributing them through the tax structure. The net financial difference between these two approaches is often smaller than buyers initially assume.
CDDs are governed under Florida's Sunshine Laws, which means that financial decisions, capital improvement plans, and budget discussions must occur in public meetings where community members can attend and observe. This creates a layer of accountability and transparency that many private HOAs do not offer.
The Pre-Listing Inspection: Why Niki Recommends It for Older Homes
St. Augustine's historic character is one of its greatest draws. The city's oldest neighborhoods contain homes that have been renovated multiple times over decades or even centuries, and those renovations vary enormously in quality, code compliance, and documentation. Buyers who fall in love with a historic property and move quickly into the purchase process can find themselves facing significant unexpected expenses after the standard inspection reveals issues the seller was not aware of.
Niki is a strong advocate for pre-listing inspections on older homes, meaning an inspection commissioned by the seller before the property goes to market. The benefit is transparency. Both parties enter the negotiation with accurate information about the home's condition. The seller can choose to address issues before listing, price the home to reflect its actual condition, or disclose known defects with a clear conscience. The buyer has fewer surprises, and the transaction is less likely to collapse at the inspection contingency stage.
For unique and high-value properties in the historic district, this matters even more. The pool of buyers who can afford a multimillion-dollar piece of historic St. Augustine real estate is small. Losing one buyer to an inspection surprise that could have been disclosed or remediated upfront can mean weeks of additional carrying costs and, in a shifting market, a lower eventual sale price.
Niki pairs the pre-listing inspection with another tool she recommends consistently: the home warranty. A seller who offers a home warranty at closing gives buyers confidence that unexpected mechanical failures during the early months of ownership will be handled. That confidence reduces the likelihood of buyers using every inspection finding as a negotiating chip. The warranty also protects the seller during the listing period itself: if the refrigerator stops working while the home is on the market, the warranty covers it.
Short-Term Rentals in St. Augustine: What the Rules Actually Say
St. Augustine's tourism economy creates genuine demand for short-term rental properties, and that demand has drawn investors from across the country. But the regulatory landscape governing short-term rentals in the area is complex enough that making a purchasing decision without hyperlocal guidance can be an expensive mistake.
Within the city limits of St. Augustine Beach, only 100 short-term rental permits exist. They are not being issued to additional properties. A buyer who purchases a property at St. Augustine Beach expecting to operate it as a short-term rental needs to verify at the time of purchase that one of those 100 permits is attached to and transferable with the home. There is no workaround.
Outside those city limits, the rules shift, and properties in other parts of the coastal area can operate short-term rentals under different frameworks. Condominiums present yet another variation. Each condominium association establishes its own rental rules, and those rules range from permitting short-term stays of a single night to requiring minimum lease terms of six months or a year. Some condominiums have strong short-term rental programs with professional management infrastructure already in place. Others prohibit it entirely.
Niki also tracks which areas of downtown St. Augustine generate the strongest short-term rental performance. Proximity to the amphitheater, which hosts events year-round, and walkability to restaurants and shopping in the historic district are key drivers of rental income. During Nights of Lights, the celebrated holiday season event that draws visitors from across the country and has been recognized as one of the premier Christmas destinations in the United States, demand for well-located downtown properties reaches its annual peak. Some investors with properties in prime locations generate enough income during that period alone to cover a substantial portion of their annual carrying costs.
"There's so many different locations that work so well as an Airbnb short-term rental type thing. You've got walking distance to the amphitheater. In the heart of downtown, especially during Nights of Lights, you've got tourist traffic. There's an event every weekend."
Pricing Unique Properties: How to Navigate Homes Without Direct Comparables
In a market as architecturally varied as St. Augustine, standard comparable sales analysis has limits. A renovated historic home in the old city might share nothing meaningful with any recent sale within the standard one-mile radius. A beachfront property with distinctive architectural features may sit within a few blocks of a similar-sized home that sold for a fraction of its value, with the difference explained entirely by orientation, view, lot characteristics, or renovation quality.
Niki addresses these situations by widening the comparable search radius when justified by the property's unique characteristics, consulting directly with other agents about pending transactions to capture the most current market sentiment, and doing brokers' opens for higher-priced properties to gather professional opinions on both pricing and condition.
Most importantly, she commits to listening to the market rather than defending an initial price that the market rejects. She tells sellers clearly that days on market is the most damaging variable in a sale process: a home that sits unsold begins to accumulate a stigma in buyers' minds that requires increasingly large price reductions to overcome. Her approach is to price precisely, monitor response during the first two weeks with genuine attention, and adjust quickly if the data suggests a recalibration is needed.
For buyers who arrive convinced that price reductions signal a market collapse, Niki uses the same data-driven approach. She looks only at comparable sales from the past three months, often narrowing further to pending transactions, and communicates directly with listing agents to understand where active contracts are landing. The goal is to help buyers write offers that reflect current market reality rather than either an outdated seller's market mindset or a crisis-driven assumption that is equally disconnected from the facts on the ground.
The St. Augustine real estate market rewards buyers and sellers who come prepared. Preparation, in Niki's definition, means working with someone who knows the city at a granular level, who can read a county development map and explain what it means for a specific neighborhood, and who treats every transaction as a personal obligation rather than a transaction to close. That is the standard she sets for herself, and it is the standard worth demanding from any agent trusted with a decision of this magnitude.
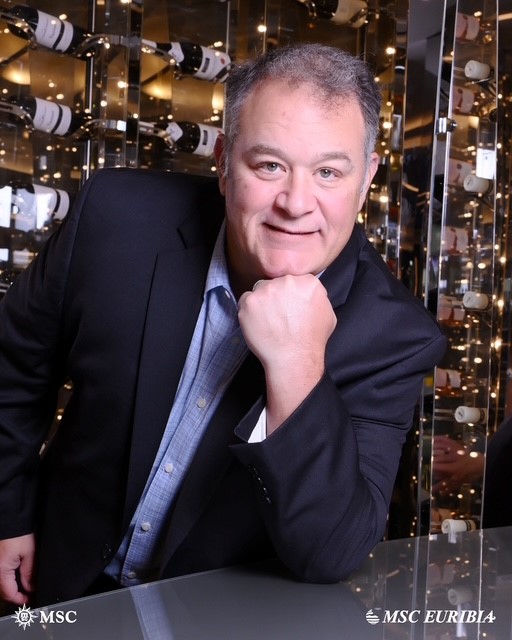
Host of Real Estate Excellence | Mortgage Loan Officer NMLS #23368
Tracy Hayes is the host of Real Estate Excellence, a podcast dedicated to bringing you real conversations with top-performing real estate professionals across Florida and beyond.
A mortgage loan officer with nearly two decades of industry experience (NMLS #23368), Tracy brings a unique perspective to every interview — combining deep lending expertise with a genuine passion for the people and stories that shape the real estate industry.
Based in Northeast Florida, Tracy has spent years building relationships with the agents, brokers, team leaders, lenders, and coaches who are setting the standard in today's market. Real Estate Excellence is his platform for sharing their unfiltered insights with agents and real estate professionals who want to grow, lead, and succeed.
Why Niki Sparks Never Made a Cold Call and Still Ranked Top 10 in St. Augustine: A Relationship-First Blueprint